|
We can also define the joint stationarity of two random processes. Two processes
Example 1 An iid random process is SSS. This is because
Example 2 The Poisson process which varies with time.
|
| Stationary Random Process Print this page | |
| << Previous | First | Last | Next >> | |
|
|
| << Previous | First | Last | Next >> |
 and
 are called jointly strict-sense stationary if their joint probability distributions of any order is invariant under the translation of time. A complex random process
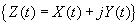 is called SSS if

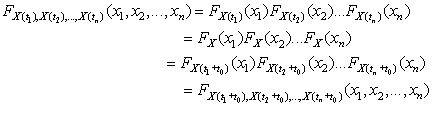
 not stationary, because
