We see that depends only on the time-lags. Thus, for a Gaussian random process, WSS implies strict sense stationarity, because this process is completely described by the mean and the autocorrelation functions.
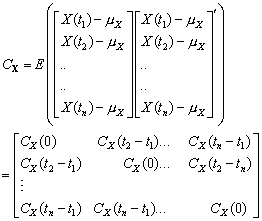
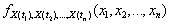 depends only on the time-lags. Thus, for a Gaussian random process, WSS implies strict sense stationarity, because this process is completely described by the mean and the autocorrelation functions.