|
Stationary Random Process The concept of stationarity plays an important role in solving practical problems involving random processes. Just like time-invariance is an important characteristics of many deterministic systems, stationarity describes certain time-invariant property of a class of random processes. Stationarity also leads to frequency-domain description of a random process. Strict-sense Stationary Process A random process
Thus, the joint distribution functions of any set of random variables Particularly, if
|
 is called strict-sense stationary (SSS) if its probability structure is invariant with time. In terms of the joint distribution function,
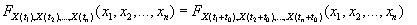
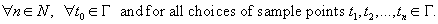
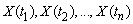 does not depend on the placement of the origin of the time axis. This requirement is a very strict. Less strict form of stationarity may be defined.
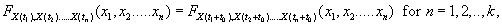 then
 is called
 order stationary.
 order stationary does not depend on the placement of the origin of the time axis. This requirement is a very strict. Less strict form of stationarity may be defined.