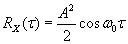Example 2 Consider the random–phased sinusoid given by where are constants and is a random variable. We have earlier proved that this process is WSS with and
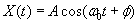 where
 are constants and
 is a random variable. We have earlier proved that this process is WSS with
 and