| Definition 1.6 (Probability measure) |
Let  be a nonempty set and  be a  -field of subsets of . A map 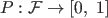 is said to be a probability measure if P satisfies |
(i)
 |
(ii) if
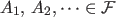 are pairwise disjoint, then |
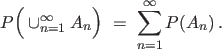 |
| |
| Definition 1.7 (Probability space). |
The triplet
 ; where , a nonempty set (sample space),  , a -field and  , a probability measure; is called a probability space. |
|
|
